

Rocco - Fast Cash Advance
4.1

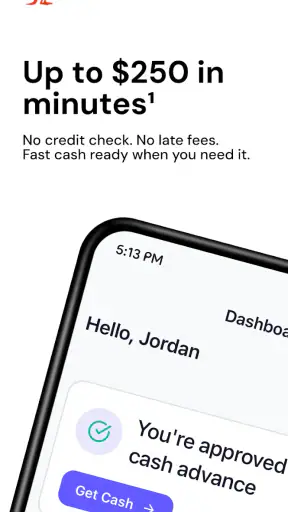
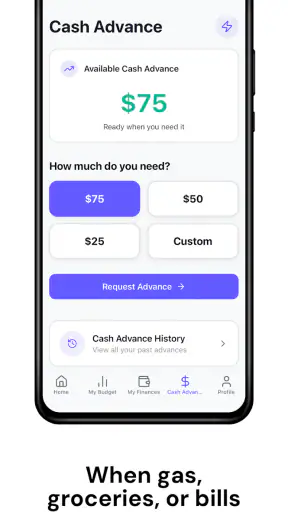
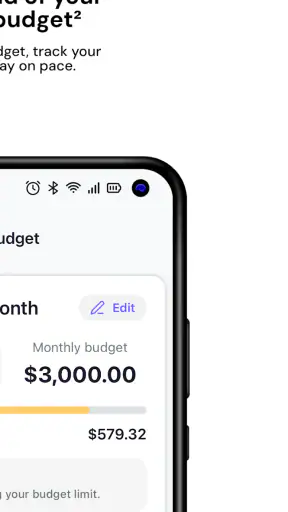
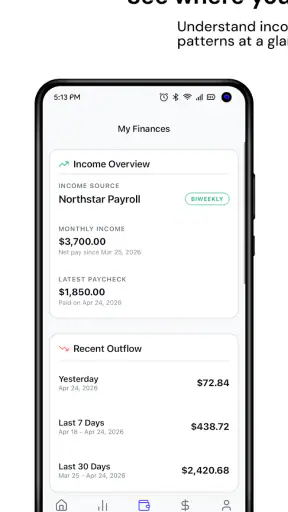
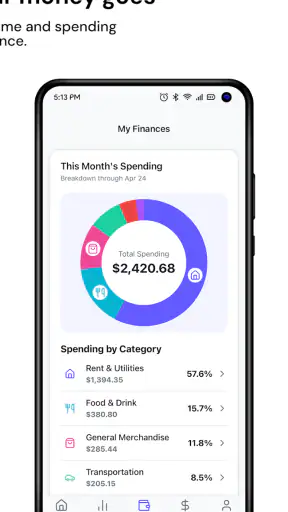
When an unexpected bill lands between paydays, the hardest part is often not finding an app but understanding what will happen next. I tried Rocco - Fast Cash Advance with that practical question in mind: can it make a short-term cash-advance request easier to handle, or does it simply move the stress into another screen? My overall impression is that it is most useful as a guided starting point for people who need to review their options quickly, while anyone looking for a complete budgeting system or a guaranteed source of money should set more modest expectations.
Rocco sits in the personal finance category and is developed by Rocco Finance, Inc. It is free to install, aimed at Everyone, and its current version is 3.0.0. The app has built a noticeable user base, with over 100 thousand installs, a 4.1 average from around 4 thousand ratings, and roughly 1.4 thousand written reviews. Those figures suggest that people are using it for a very specific need rather than treating it like a general-purpose banking replacement.
From a cash shortfall to a clearer decision
Starting with the actual problem
The most sensible way to approach Rocco is to begin with the reason you opened it. If I am short because a utility payment is due before my next paycheck, I want to know three things immediately: whether I can make a request, what information I must provide, and what the repayment consequences could be. An app with a cash-advance focus should be judged by how clearly it handles that chain, not merely by how quickly its first screen appears.
That distinction matters because a cash advance is not extra income. It is a temporary solution that changes the timing of money already expected later. I would use Rocco only after checking the exact amount needed and identifying the next reliable income date. Asking for more than the gap can turn a manageable shortage into a second shortage when repayment arrives.
The app’s store summary presents it as a combination of cash advance and personal finance services. In practice, that positioning makes it more focused than a standard expense tracker. You are not opening it primarily to categorize years of spending or build an investment portfolio. You are opening it to explore a short-term financial option and move through the information required to assess it.
Working through the first screens
The initial flow is best treated as an assessment rather than a promise. I would read every prompt carefully, enter only accurate information, and avoid rushing simply because the word “fast” appears in the product name. Finance apps often depend on details that look routine but affect eligibility, identity checks, repayment timing, or the amount that can be considered.
A useful habit is to keep the purpose of the request consistent from beginning to end. If the need is a grocery gap, calculate that gap before starting. If it is a bill, have the bill amount and due date in front of you. This makes the process less abstract and helps prevent the common mistake of accepting an amount that feels convenient in the moment but is difficult to absorb later.
I also recommend pausing at any page that explains terms, repayment, or account handling. The most important screen is not necessarily the one that shows a potential advance. It is the one that tells you what accepting the arrangement means. If the wording is unclear, that is a reason to stop and investigate, not a reason to tap through faster.
Information handoffs and why they matter
The central handoff in this kind of workflow is between you and the financial service: you supply personal and financial details, the service evaluates the request, and you receive an outcome or additional instructions. Rocco is therefore only one part of the process. It can organize the request experience, but it cannot remove the need for accurate information or guarantee that every user will receive the same result.
This is where I would separate convenience from certainty. A smooth interface may reduce typing and make the next step obvious, but approval, availability, timing, and repayment still depend on circumstances outside the visual design of the app. Treating an on-screen estimate as guaranteed cash is the wrong mental model.
Another handoff occurs when the app directs you toward an external financial step or asks you to review information connected with your finances. I would check that the account or details belong to me, use a secure connection, and avoid completing the process on a shared device. I would also keep a record of what I submitted and what repayment information I saw, especially if the request is made during a stressful moment.
The most important workflow tip is to save the decision for the repayment check. Before accepting anything, I would compare the expected repayment with the next paycheck after rent, food, transport, and existing obligations are removed. A request that solves today’s problem but creates a larger gap next week is not a successful outcome.
A realistic everyday scenario
Imagine that my phone bill is due on Friday, but my paycheck arrives the following Monday. I would first confirm the exact shortfall rather than opening Rocco with a vague feeling that I need “some money.” I would then review the app’s available path, provide the requested information, and examine the resulting terms or next steps. If the repayment fits comfortably after Monday’s essential expenses, the service may be worth considering.
If the same scenario involved rent, a medical bill, or an amount that would consume most of my next paycheck, my decision would change. I would look for a lower-cost arrangement first, such as contacting the bill provider, requesting a payment extension, or using an existing emergency fund. Rocco may help me explore a short-term option, but it should not be the first answer to a recurring monthly deficit.
This is also where the personal-finance side of the app can be useful as a prompt for better thinking, even if the immediate goal is an advance. I would write down the upcoming obligations before submitting a request. That simple step exposes whether the problem is a one-time timing mismatch or evidence that the monthly budget is already underwater.
What the result means in practical terms
A good result from Rocco is not simply seeing a number appear. The useful result is reaching a clear decision with a realistic understanding of the next action. That might mean continuing with an eligible request, reviewing additional instructions, or deciding that the repayment burden is not appropriate. An app earns trust when it helps me make that choice without disguising the trade-off.
For a person who is comfortable reading financial terms and needs a focused route to investigate a short-term advance, the app can be more convenient than searching randomly across unrelated services. Its narrow purpose reduces the distraction found in broad budgeting apps, where a user may spend time building categories while an urgent bill remains unresolved.
At the same time, I would not confuse Rocco with a bank account, a paycheck replacement, or a long-term debt-management tool. The app’s role is closer to a gateway into a cash-advance and personal-finance service workflow. That makes it potentially helpful for an isolated timing problem, but limited as a complete plan for improving financial health.
Where the flow can break
The first point of friction is eligibility. Installing a finance app does not mean that every user will qualify for an advance, receive the amount they want, or receive funds on the schedule they expect. Because the outcome depends on the information and circumstances involved, I would never download Rocco with a bill due in the next hour and assume the app can solve it.
The second problem is repayment timing. Even a small advance can be uncomfortable when several automatic payments are already scheduled. I would check my bank balance and upcoming commitments before accepting anything. If the app presents a repayment date that collides with rent, utilities, or food spending, the correct response is to step back and seek another arrangement.
A third concern is repetition. The workflow may feel manageable once, but relying on advances every pay cycle points to a structural issue that an advance app cannot fix. In that situation, a detailed budgeting tool, a conversation with creditors, or a nonprofit financial counselor may be more useful. Rocco is not the right choice when the underlying need is debt restructuring rather than a brief timing bridge.
There is also a privacy and attention cost to consider. Finance workflows require careful handling of personal information, and I would not treat any app as a place to tap through automatically. I would review each request, keep the operating system updated, and remove access or stop the process if a screen asks for something I do not understand. Speed is valuable only when it does not replace judgment.
How it compares with familiar alternatives
Compared with a traditional bank’s overdraft or short-term credit option, Rocco may feel more direct because it is built around the cash-advance question rather than a full banking relationship. A bank may be preferable for users who already understand their account terms and want everything managed in one established place. The trade-off is that a bank’s process may be less focused on the immediate advance workflow.
Compared with a budgeting app, Rocco addresses the urgent cash-flow gap first. A budgeting app is usually better for spotting recurring overspending, planning categories, and building a longer-term buffer. If I am constantly short before payday, I would choose the budgeting route as the main tool and treat Rocco, at most, as a temporary option to investigate carefully.
Compared with borrowing from a friend or family member, the app offers a more formal and self-directed process, but personal borrowing can sometimes be cheaper or more flexible when trust and repayment expectations are clear. Compared with a credit card, the better choice depends on the terms, existing balance, and ability to repay. There is no universal winner; the important comparison is the total obligation and whether it fits the next several weeks of real expenses.
Who will get the most from it
I see Rocco working best for an adult who has a short, identifiable cash-flow mismatch, understands that an advance must be repaid, and is willing to inspect the details before agreeing. It can also suit someone who wants a focused financial-service app rather than a large banking platform filled with unrelated features.
I would be more cautious recommending it to a first-time borrower, someone with irregular income, or anyone already juggling several repayment commitments. Those users need clarity above all else, and a fast application flow can make a difficult decision feel easier than it really is. The app may still be worth reviewing, but not as an automatic solution.
It is also a poor fit for anyone seeking investing tools, full expense analytics, bill negotiation, or a permanent replacement for an emergency fund. The personal-finance label should not be read as evidence that it covers every part of money management. Its strongest identity remains the short-term cash-advance workflow.
My practical setup before using it
Before opening the app, I would prepare the amount needed, the reason for it, the next dependable income date, and a list of essential payments due before then. I would also decide in advance what repayment amount would make the request unacceptable. Setting that boundary before seeing an offer protects against making an emotional decision after a stressful day.
During the process, I would take time with every summary screen and keep screenshots or notes of important dates and amounts where appropriate. Afterward, I would add the repayment to my calendar and check my account several days beforehand. This is a small but valuable handoff from the app to my own financial routine: the service may show the obligation, but I am responsible for making sure the money is available.
If the request does not work, I would not repeatedly submit applications without understanding why or what effect that could have. I would contact the bill provider, review alternatives, and use the experience as evidence about the size of my emergency buffer. A declined or unsuitable result is still useful if it prevents me from taking on an obligation I cannot comfortably carry.
My final view after following the workflow
Rocco - Fast Cash Advance is a focused free finance app from Rocco Finance, Inc. that can help users investigate a short-term cash need through a more direct path than a general budgeting application. Its 2022 release and current 3.0.0 version show an established product rather than a brand-new experiment, while its Everyone content rating makes it broadly accessible to its intended audience.
My recommendation is conditional but positive: use it when the shortage is temporary, the repayment plan is understandable, and the next income is dependable. Do not use it as permission to spend beyond your means or as a substitute for fixing a recurring budget problem. The app’s real value is not the promise of instant relief; it is the chance to turn a vague cash emergency into a sequence of checks, decisions, and responsibilities.
If I were advising a friend, I would say to install it only after calculating the gap, then move slowly through the request and judge the outcome by what happens after repayment. For a one-off timing problem, that discipline can make Rocco a practical option. For ongoing financial pressure, I would choose a broader budgeting or debt-support approach instead and keep this app out of the center of the plan.
4.1
1.38K Reviews
Pros
- Simple application process with minimal paperwork
- Fast eligibility checks can save time in emergencies
- Clear repayment schedule helps users plan ahead
- Useful for covering unexpected short-term expenses
- Mobile access lets users apply from almost anywhere
Cons
- High fees or APR may make borrowing expensive
- Loan availability depends on location and eligibility
- Late payments can lead to additional charges
- May require access to sensitive personal and financial data
- Short repayment periods can strain limited budgets


